Trusted by institutions building next-gen finance


the basics
What is first-party fraud?
First-party fraud is when a real customer, using their own identity, deliberately misrepresents themselves or misuses a product for gain. Nobody's identity is stolen, so identity checks pass, and the customer looks good right up until the loss. Here's how it differs from what it's mistaken for:
Third-party fraud: someone else uses the victim's identity or account
Credit loss: the customer meant to pay and couldn't
First-party fraud: the customer never meant to pay, or to keep the purchase
Friendly fraud: a disputed chargeback, sometimes by mistake

Chargeback Fraud

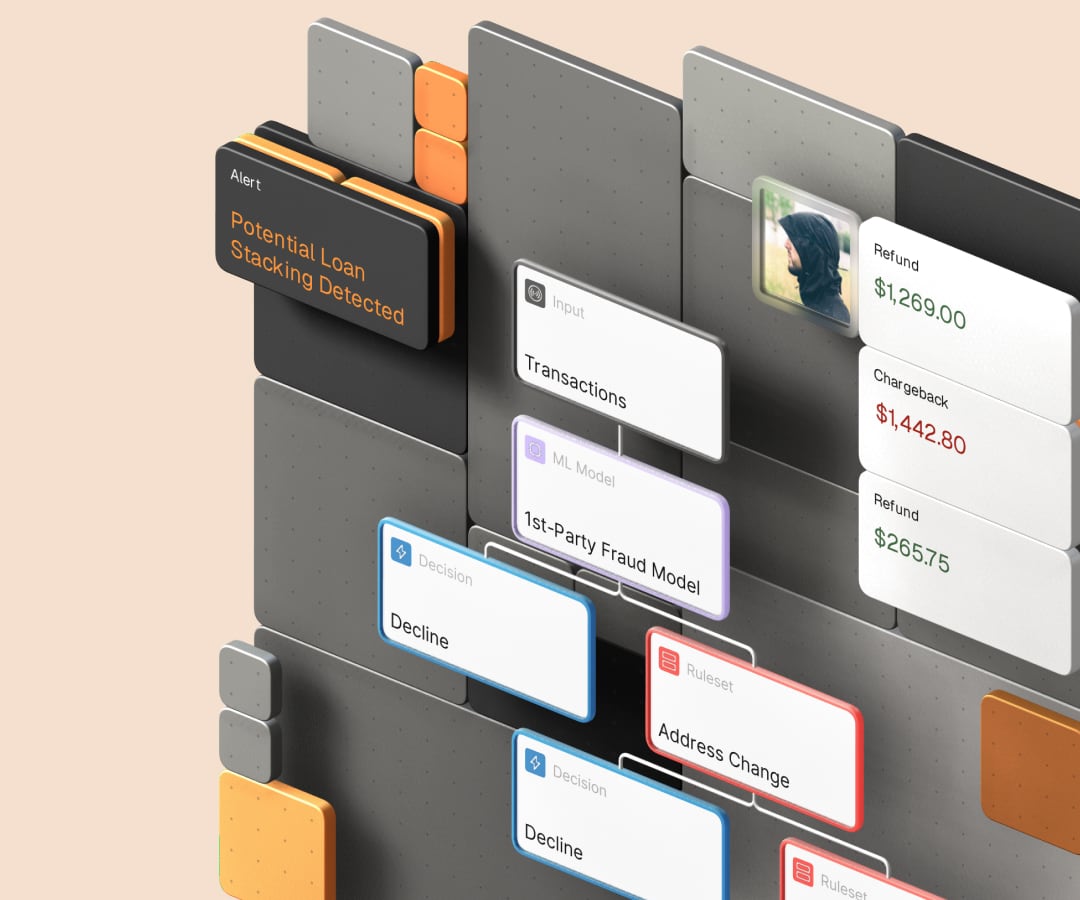
Loan Stacking
Application Fraud

Bust-Out Fraud
Ghost Funding
First-Payment Default
workflow assistance
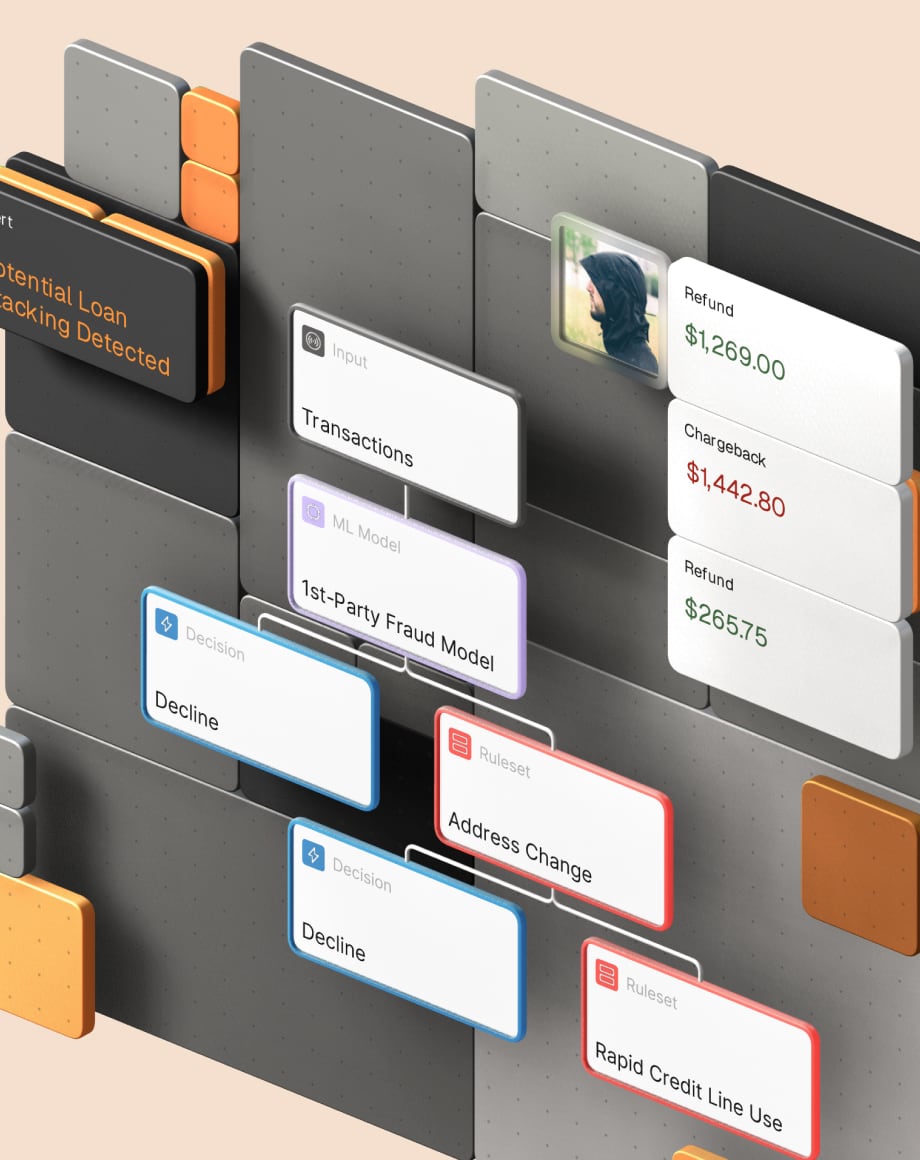
Build first-party fraud workflows in plain language.

AI-Powered Workflow Creation
Describe your first-party fraud policy in natural language and Oscilar AI turns it into rules and workflows you can review before they go live.

Leverage Pre-Built Rules and ML Models
Start from rules and models for bust-out, loan stacking, first-payment default and chargeback abuse, then tune them to your products.

Powerful Testing Suite
Backtest new first-party fraud rules on your own history before they touch a live customer, and A/B test them once they do.

comprehensive security
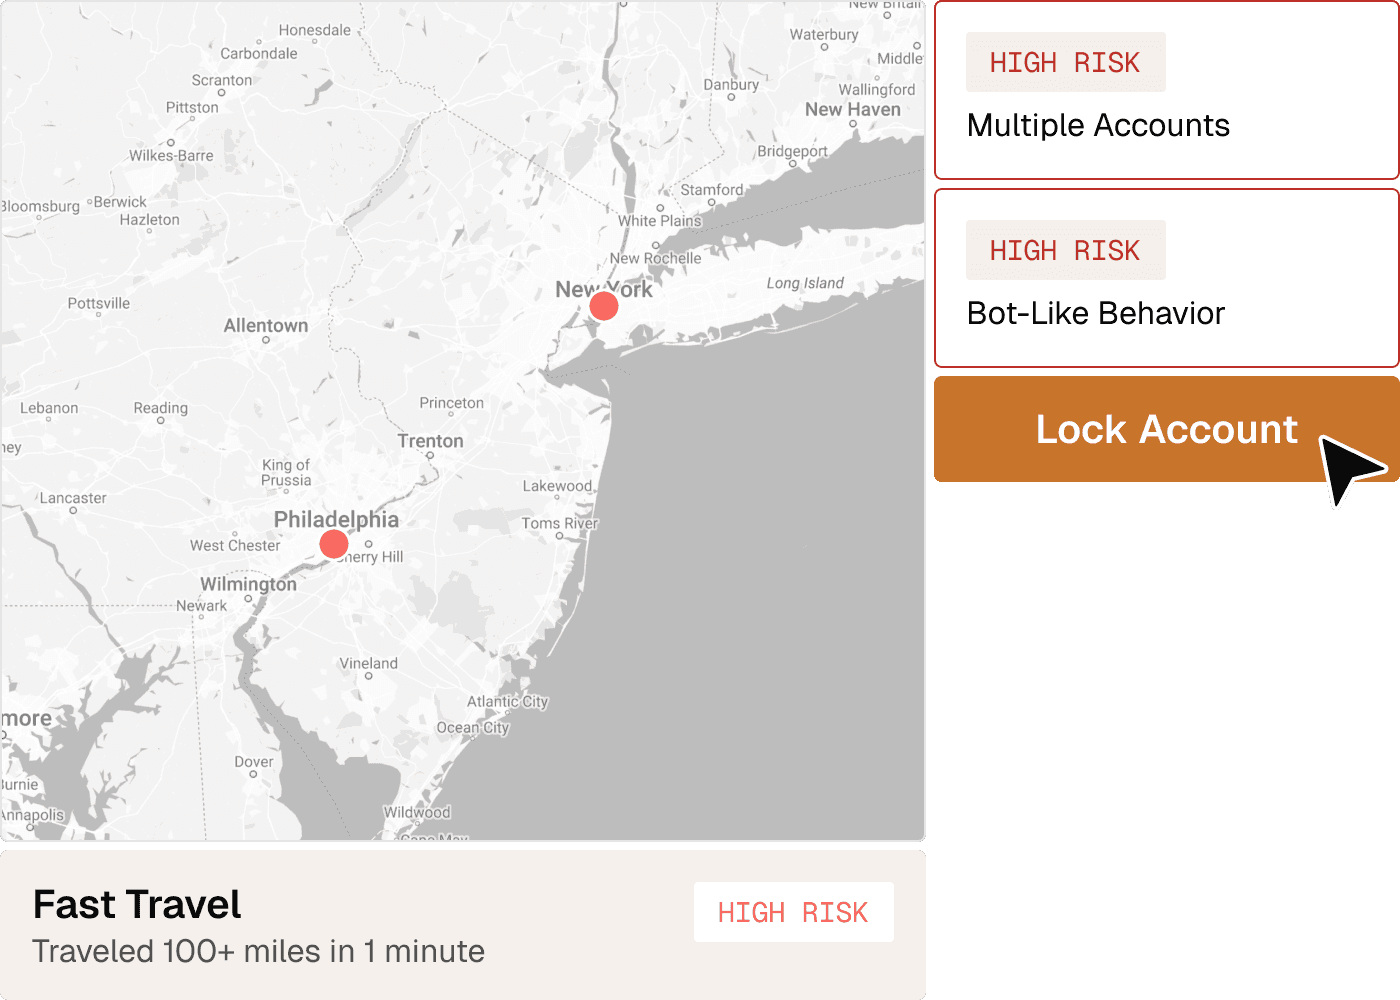
Obtain a true 360° view of your users and their activity with device intelligence, behavioral signals, and more.

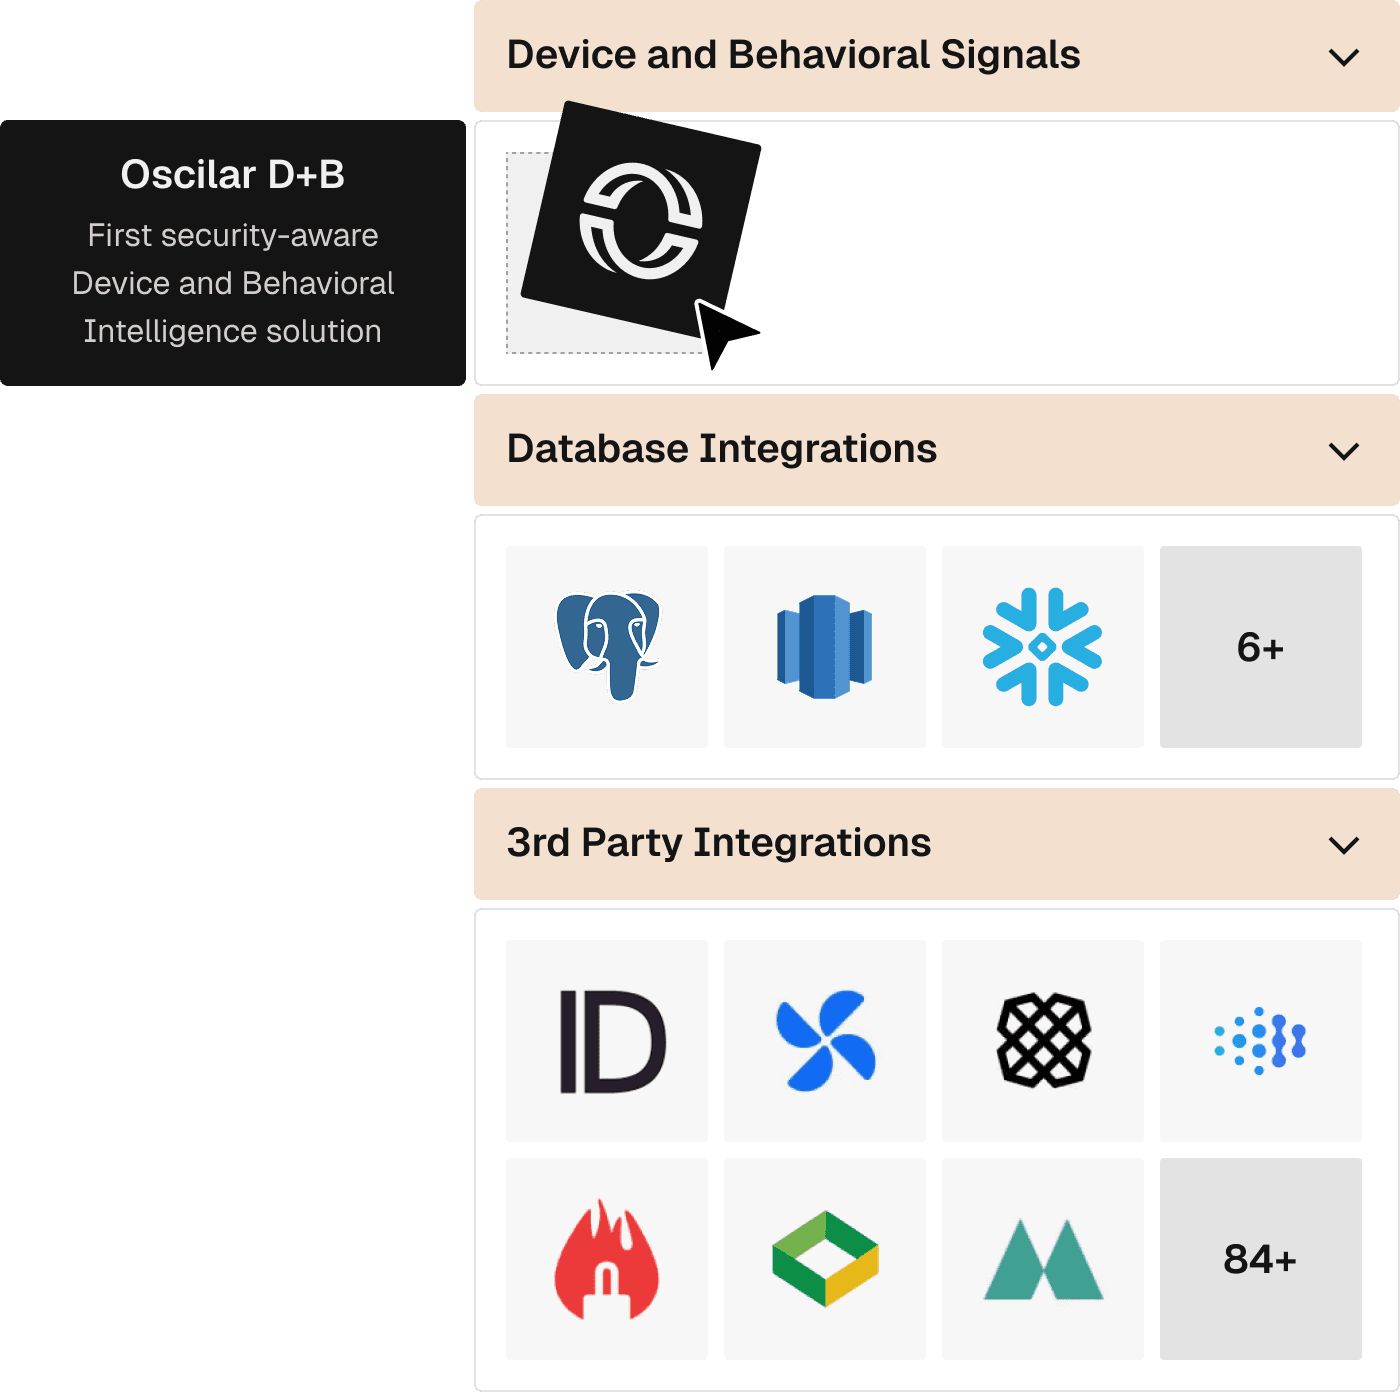
Security-Aware Device and Behavioral Intelligence
Oscilar’s advanced D+B product provides state-of-the-art encryption and obfuscation to ensure security and prevent spoofing and reverse engineering.

Advanced Device and Behavioral Signals
Enhance customer identification and prevent account takeovers with device intelligence, behavior biometrics, and data enrichments.

Effortless 1st Party Data and Marketplace Integration
Connect your databases with one click using our automated ingestion system, and add third-party data sources through the Oscilar Marketplace.
comprehensive detection
First-party fraud shows up over time, so detection has to as well.
No single signal proves intent. Oscilar scores the combination, from application through the life of the account, so a genuine customer in a rough month isn't treated like a planned bust-out.
At application: inquiry velocity across lenders and details that conflict with bureau data
Early life: first-payment default, funding-source changes and deposits that reverse
In life: sudden utilization against history, payment reversals and repeated disputes
Across accounts: shared devices, identities and funding sources linking customers

efficiency gains
Streamline investigations with AI-driven Case Management.

Intelligent Prioritization
Cases ranked by urgency and exposure, and routed to first-party fraud queues so specialists see them first.

Holistic User View
Access all historical and real-time data about the user and their activity at your fingertips.

AI Case Insights
A plain-language explanation of why each case opened and what points to intent rather than hardship, so reviewers document every call consistently.
Customers see results with Oscilar.

FAQ
Glad you asked.
Is friendly fraud the same as first-party fraud?
Not quite. Friendly fraud usually means a chargeback dispute on a legitimate purchase, sometimes made by mistake. First-party fraud is deliberate, and it covers credit, deposits and payments as well as card disputes. Most deliberate friendly fraud is one kind of first-party fraud.
How is first-party fraud different from third-party fraud and credit risk?
In first-party fraud, the legitimate customer or applicant is the actor; third-party fraud involves an external actor using stolen accounts, credentials, or identities. Credit risk usually reflects an inability to repay, while first-party fraud involves deliberate deception or misuse. The outcomes can look similar, so institutions need longitudinal behavior, application and portfolio data, linkages, and review processes rather than a single fraud rule.
What are common types of first-party fraud in financial services?
Common types include falsifying application information, opening multiple loans before bureaus update, making no first payment, building credit before a bust-out, disputing legitimate purchases, abusing refunds or promotions, and moving funds through accounts under the customer's control. The relevant typologies vary by lending, cards, deposits, payments, and commerce, so detection should be tailored to the product and customer journey.
How do financial institutions distinguish deliberate misuse from genuine financial distress?
No single signal proves intent. Institutions should compare repayment and delinquency patterns, utilization, income and balance changes, account activity, application representations, linked accounts, devices, behavioral signals, and prior disputes. Contradictory evidence and plausible hardship explanations should be considered. When confidence is limited, use proportionate actions and human review rather than automatically labeling a customer as fraudulent.
Which behavioral and portfolio signals can reveal first-party fraud before losses materialize?
Useful indicators can include rapid utilization, sudden spending or transaction velocity relative to history, multiple applications or accounts, funding-source changes, first-payment default, repeated chargebacks, unusual limit usage, shared devices or identities, and coordinated activity across linked accounts. These signals are stronger in combination and over time. Oscilar can combine first-party, device, behavioral, transaction, and network data in configurable decision workflows.
How should first-party fraud decisions be documented when intent is uncertain?
Record the evidence and its source, the behavioral timeline, relevant rule or model reason codes, the policy applied, alternative explanations considered, the analyst's rationale, any override, and the action taken. Documentation should distinguish observed facts from an inference about intent. Proportionate interventions, quality review, appeal or reconsideration paths, and outcome feedback help teams act consistently without overstating what the evidence proves.

" height="48px" id="Qi9pnIQwR" width="48px"/></g></svg>)
" height="39.77194px" id="A8r2uGwai" transform="translate(2 3.808)" width="44px"/></svg>)

