Trusted by institutions building next-gen finance


AML Transaction Monitoring
Streamline regulatory compliance and minimize false positives.
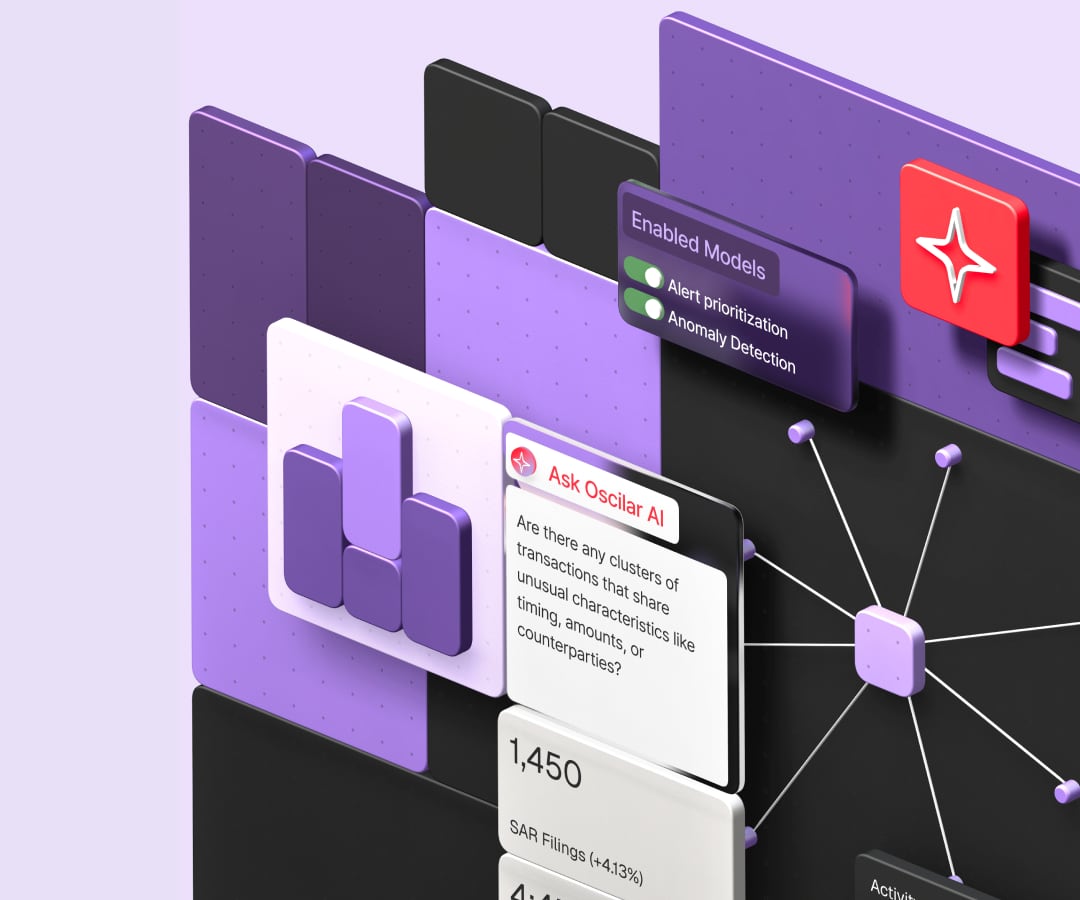
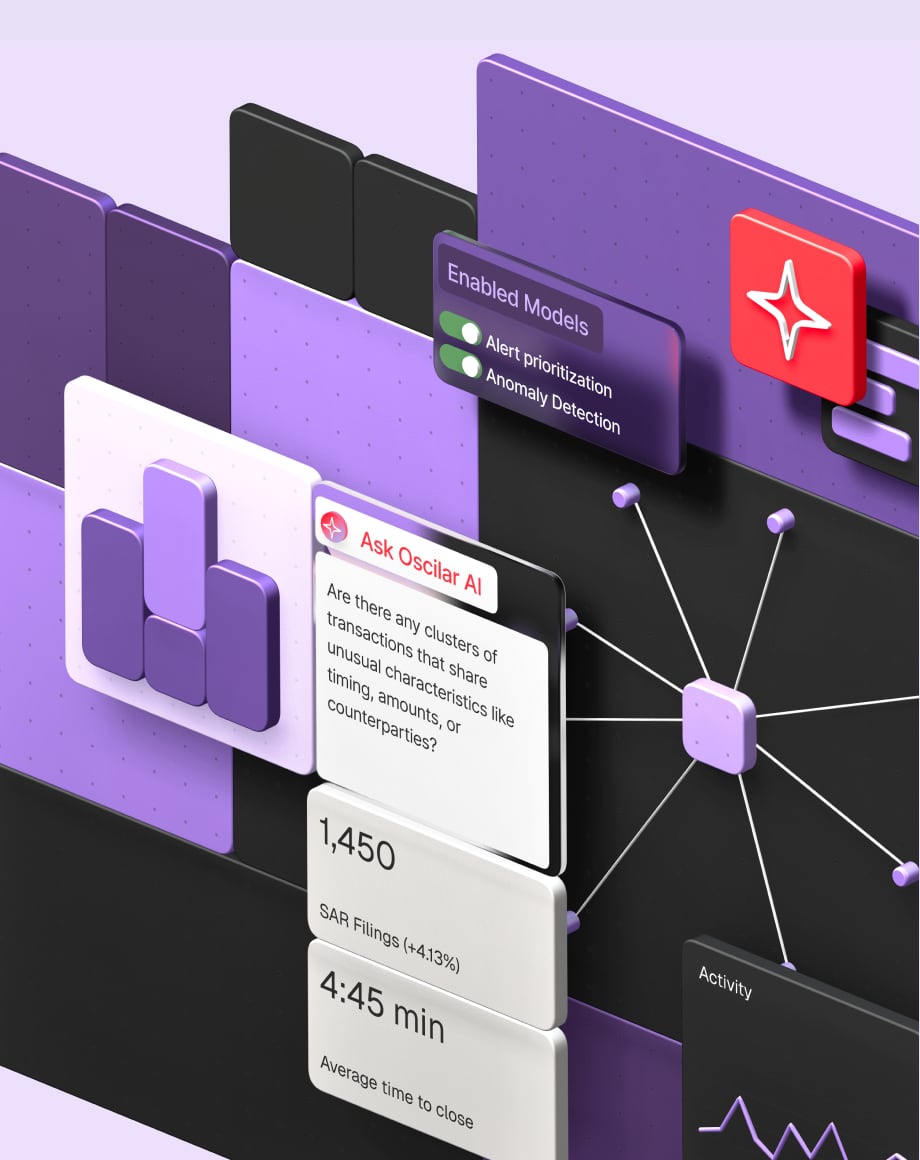
Analyze every transaction in milliseconds, using sophisticated ML algorithms to detect suspicious patterns that traditional rule-based systems miss.
Real-time and batch transaction analysis
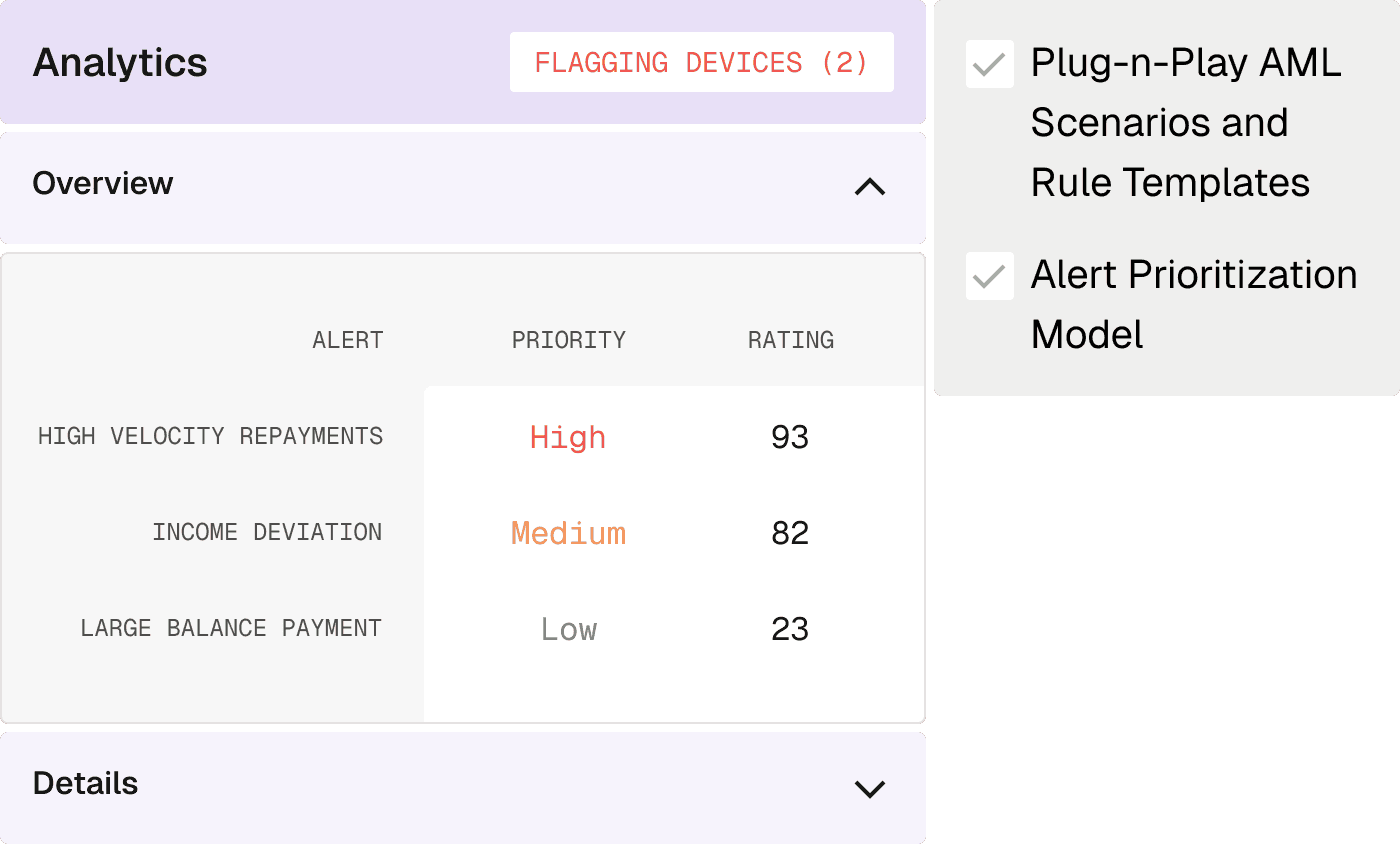
Pre-built, adaptable rulesets for current money laundering detection
Advanced ML models with 95% detection accuracy
Continuous learning and adaptation
KYC/KYB Automated Onboarding
Reduce your manual verification workload without sacrificing thoroughness.
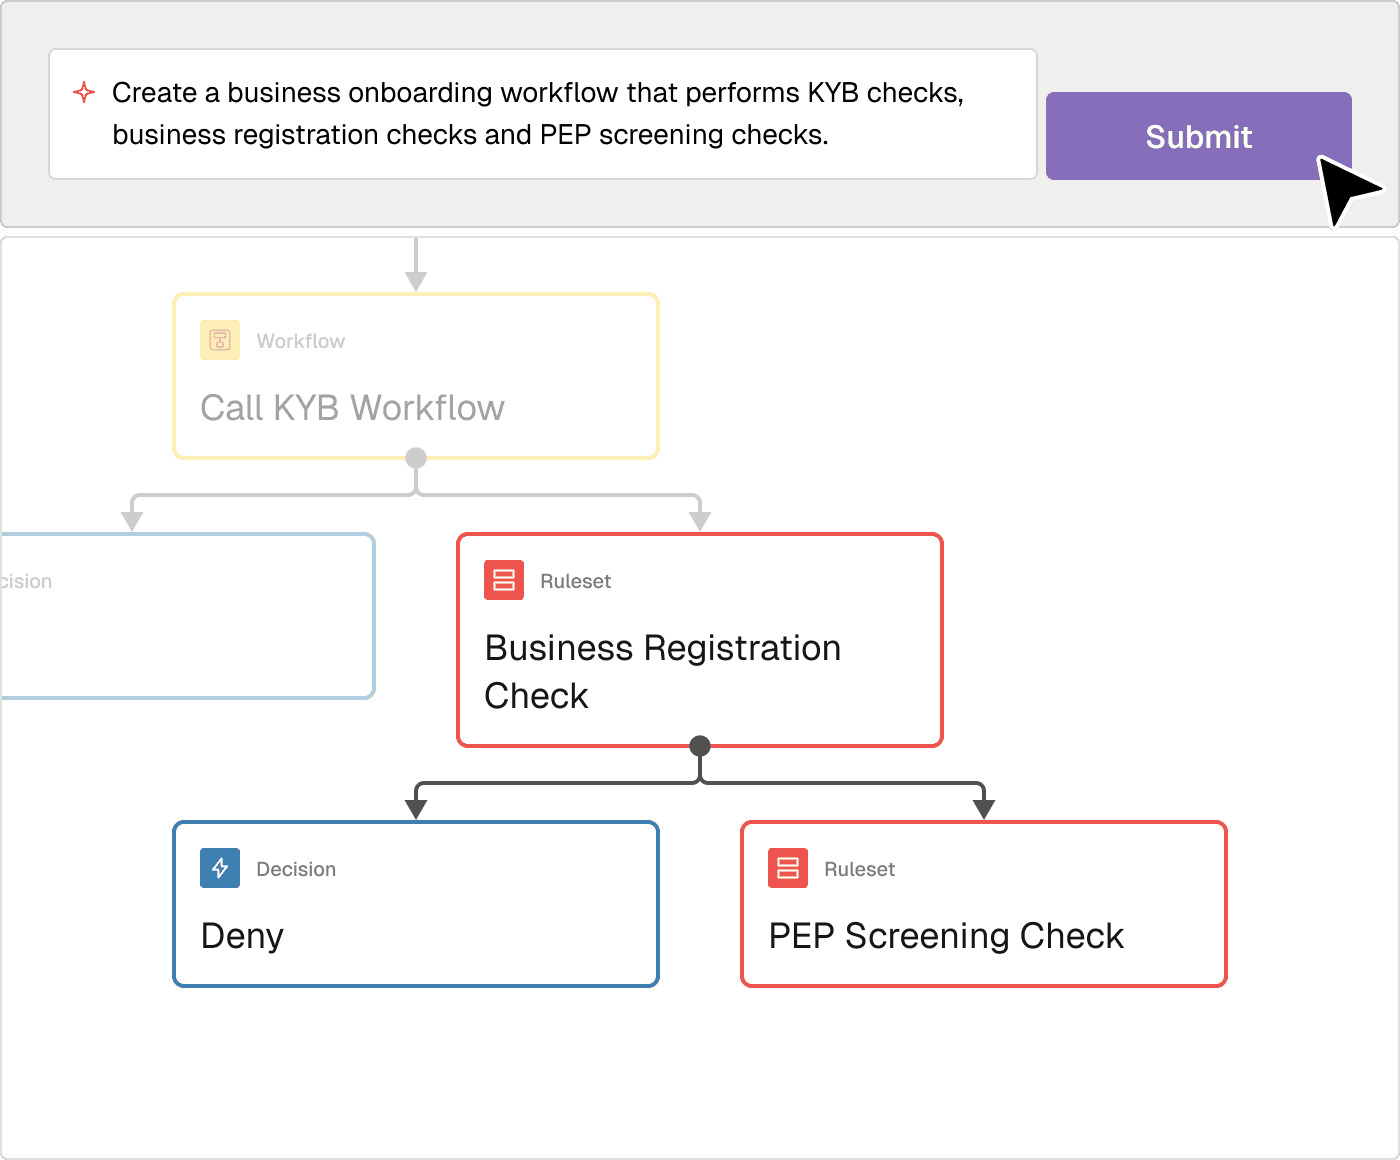
Transform your customer onboarding process with intelligent automation that maintains rigorous compliance standards while accelerating legitimate customer acquisition.
Streamlined customer onboarding with automated verification
Advanced data analysis and verification technologies
Compliance assurance with reduced manual errors
Integration with 80+ third-party data sources
FRAML (Fraud + AML)
Improve visibility across the entire customer lifecycle.
Break down operational silos with Oscilar's unified FRAML approach that combines fraud prevention and AML compliance into a single, comprehensive risk management strategy.
Unified view of fraud and AML risks
Enhanced collaboration between teams
Comprehensive risk assessment across customer journey
Proactive prevention of financial crime


AI-Powered Insights
Understand the context behind a case. Oscilar AI helps surface details and uncovers connections, pointing you towards potential resolutions faster.

Dynamic Risk Scoring
Continuously assess and score risk profiles using advanced analytics and ML. Dynamically adjust with new data so you can be more proactive.
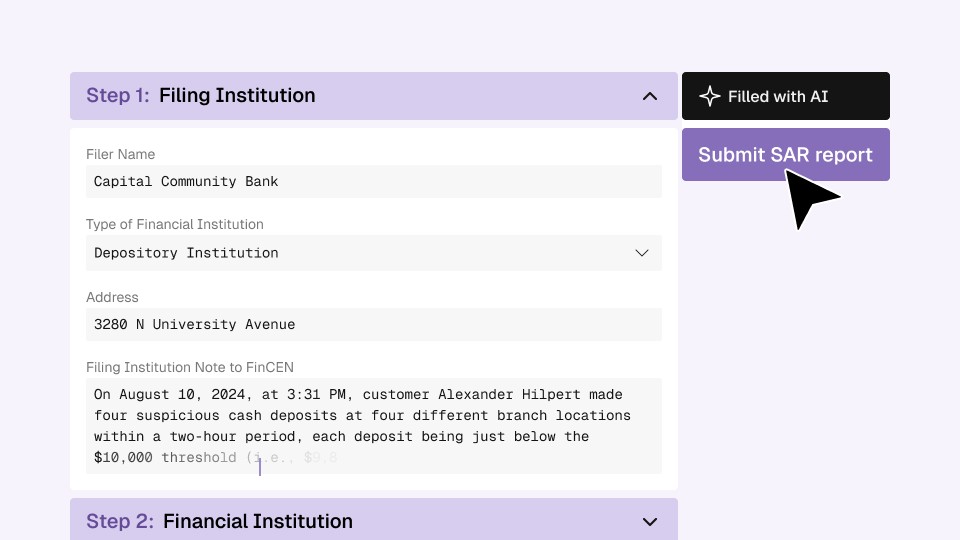
SAR Automation & E-Filing
Say hello to direct, automated FinCEN SAR filing. Pre-populated templates streamline your submissions so you can stay in compliance.

Unify Your Risk
Ditch the point solutions and fragmented tool chain. Monitor all your risk in one platform.

Fight Modern Threats
AI doesn't just accelerate the good guys. Fight fire with fire using AI that keeps you one step ahead.

Innovate Faster
Adjusting your strategy on the fly has never been easier. Make changes quickly and backtest against historical data.
Customers see results with Oscilar.


FAQ
Glad you asked.
What is AML transaction monitoring for banks?
AML transaction monitoring is the risk-based process of reviewing customer and account activity to identify patterns that may indicate money laundering or other suspicious behavior. It combines transaction data with customer, product, geography, and historical context to create alerts for investigation. It is one part of a broader BSA/AML program, alongside customer due diligence, sanctions controls, case management, reporting, and governance.
How is modern AML transaction monitoring different from rules-based monitoring?
Rules remain useful for explicit policies and known typologies, but rules alone tend to evaluate fixed conditions in isolation. Modern monitoring combines configurable rules with behavioral baselines, anomaly detection, customer risk, network context, and alert prioritization. The goal is not to replace rules with a black box; it is to add context, testability, and adaptive detection while preserving explainable controls and human review.
How can a bank modernize transaction monitoring without replacing every upstream system?
Modernization can be phased. A bank can keep upstream data sources and an incumbent monitoring system while adding a decisioning or investigation layer that normalizes alerts, enriches them with customer context, and improves routing and review. The key requirements are reliable data mapping, reconciled alert counts, clear system ownership, and a controlled migration plan. Oscilar's modular agents can consume alerts from existing monitoring systems, while its broader platform can unify data and workflows when a bank is ready.
How can banks reduce AML false positives without weakening detection coverage?
Reducing false positives should come from better context and testing, not simply suppressing alerts. Banks can segment customers and products, enrich activity with risk and behavioral signals, prioritize alerts, and tune scenarios against historical outcomes. Every change should be backtested for both workload and missed-risk effects, then monitored after release. Oscilar supports rules, models, testing, and prioritization in the same decisioning environment.
What governance controls should a bank expect for model validation, rule changes, and examiner review?
A bank should be able to identify every rule and model owner, preserve versions, document approvals, test changes against historical data, monitor performance after release, and reconstruct the inputs and rationale behind a decision. Human overrides and exceptions should also be logged. Oscilar supports backtests, A/B tests, and unit tests for risk workflows; its agents retain the input, reasoning, and output for review. The bank still owns validation standards, approval authority, and regulatory accountability.
How should a platform support multiple lines of business while preserving centralized oversight?
Use a common data model, control taxonomy, case standard, and reporting layer across the bank, while allowing each line of business to configure its own products, thresholds, workflows, and escalation paths. Central teams should see versions, approvals, exceptions, and performance without forcing identical policies everywhere. Oscilar's unified platform connects data across risk touchpoints and lets teams create, test, and adjust tailored workflows, supporting local risk decisions within a shared operating and oversight framework -- without forcing every business into identical controls.
" height="48px" id="Qi9pnIQwR" width="48px"/></g></svg>)
" height="39.77194px" id="A8r2uGwai" transform="translate(2 3.808)" width="44px"/></svg>)


" height="22.301126233991734px" id="PeyDPUyWO" transform="translate(45.365 4.852)" width="20.043580159797898px"/><path d="M 13.46 11.116 C 12.368 10.493 10.888 9.973 9.024 9.556 C 7.664 9.236 6.613 8.927 5.887 8.624 C 5.155 8.321 4.647 7.979 4.355 7.59 C 4.064 7.201 3.921 6.704 3.921 6.104 C 3.921 5.184 4.269 4.447 4.972 3.898 C 5.675 3.349 6.624 3.069 7.83 3.069 C 8.79 3.069 9.607 3.241 10.282 3.578 C 10.951 3.921 11.482 4.401 11.876 5.018 C 12.265 5.641 12.511 6.361 12.614 7.184 L 16.1 6.973 C 15.94 5.63 15.523 4.435 14.854 3.383 C 14.185 2.332 13.265 1.503 12.105 0.903 C 10.945 0.303 9.539 0 7.899 0 C 6.355 0 5.024 0.263 3.904 0.783 C 2.783 1.303 1.92 2.035 1.32 2.978 C 0.72 3.921 0.417 5.001 0.417 6.224 C 0.417 7.344 0.646 8.281 1.109 9.036 C 1.572 9.785 2.315 10.419 3.349 10.928 C 4.384 11.436 5.755 11.905 7.481 12.328 C 9.024 12.688 10.19 13.059 10.985 13.442 C 11.774 13.825 12.311 14.237 12.591 14.688 C 12.871 15.14 13.014 15.666 13.014 16.266 C 13.014 16.906 12.848 17.455 12.517 17.906 C 12.185 18.358 11.705 18.695 11.076 18.912 C 10.448 19.135 9.676 19.243 8.779 19.243 C 7.739 19.243 6.847 19.072 6.104 18.735 C 5.361 18.392 4.778 17.883 4.344 17.203 C 3.915 16.523 3.629 15.689 3.486 14.711 L 0 14.923 C 0.103 16.403 0.514 17.7 1.246 18.798 C 1.977 19.901 2.972 20.764 4.235 21.381 C 5.498 22.004 6.99 22.313 8.71 22.313 C 10.27 22.313 11.636 22.061 12.797 21.564 C 13.957 21.061 14.871 20.341 15.528 19.398 C 16.191 18.455 16.523 17.346 16.523 16.06 C 16.523 15.02 16.289 14.094 15.814 13.282 C 15.346 12.471 14.563 11.756 13.471 11.133 Z" fill="rgb(20, 20, 20)" height="22.312556870217108px" id="ZaBOTiDLx" transform="translate(68.34 4.858)" width="16.522951309374434px"/><path d="M 13.682 17.877 C 12.751 18.792 11.442 19.243 9.762 19.243 C 8.522 19.243 7.43 18.923 6.504 18.283 C 5.572 17.643 4.847 16.723 4.326 15.517 C 3.806 14.317 3.543 12.871 3.543 11.191 C 3.543 9.51 3.801 8.093 4.309 6.876 C 4.818 5.664 5.544 4.727 6.487 4.064 C 7.43 3.401 8.533 3.069 9.79 3.069 C 11.373 3.069 12.619 3.486 13.534 4.315 C 14.443 5.149 15.031 6.281 15.294 7.727 L 18.901 7.544 C 18.438 5.178 17.472 3.332 16.003 2 C 14.528 0.669 12.459 0 9.796 0 C 7.83 0 6.115 0.457 4.641 1.366 C 3.166 2.28 2.029 3.572 1.217 5.241 C 0.406 6.916 0 8.893 0 11.179 C 0 13.465 0.412 15.494 1.235 17.146 C 2.058 18.798 3.201 20.072 4.675 20.964 C 6.15 21.855 7.847 22.301 9.767 22.301 C 11.528 22.301 13.054 21.975 14.334 21.324 C 15.614 20.672 16.654 19.752 17.443 18.558 C 18.232 17.363 18.758 15.957 19.021 14.334 L 15.443 14.151 C 15.203 15.711 14.614 16.952 13.682 17.86 Z" fill="rgb(20, 20, 20)" height="22.301126257066386px" id="dj2F9fN0f" transform="translate(87.772 4.841)" width="19.020540282808156px"/><path d="M 0 21.335 L 0 0 L 3.423 0 L 3.423 21.335 Z" fill="rgb(20, 20, 20)" height="21.335239445830055px" id="fvIs54YbW" transform="translate(110.485 5.332)" width="3.423468638642248px"/><path d="M 3.429 0 L 0 0 L 0 21.341 L 13.762 21.341 L 13.762 18.272 L 3.429 18.272 Z" fill="rgb(20, 20, 20)" height="21.340954752405395px" id="KykvynROU" transform="translate(118.389 5.332)" width="13.762458233473922px"/><path d="M 9.859 3.303 L 16.077 21.335 L 19.684 21.335 L 11.991 0 L 7.693 0 L 0 21.335 L 3.635 21.335 L 9.853 3.303 Z" fill="rgb(20, 20, 20)" height="21.33523944583004px" id="Ln_a1JZTX" transform="translate(133.986 5.338)" width="19.683515845550573px"/><path d="M 11.545 12.499 C 12.968 12.059 14.043 11.322 14.774 10.293 C 15.506 9.259 15.871 8.024 15.871 6.584 C 15.871 4.521 15.191 2.909 13.825 1.743 C 12.465 0.583 10.539 0 8.053 0 L 0 0 L 0 21.335 L 3.423 21.335 L 3.423 13.071 L 8.201 13.071 L 12.802 21.335 L 16.529 21.335 L 11.539 12.499 Z M 11.173 9.116 C 10.402 9.705 9.327 10.002 7.944 10.002 L 3.435 10.002 L 3.435 3.058 L 7.944 3.058 C 9.327 3.058 10.402 3.361 11.173 3.961 C 11.945 4.561 12.328 5.435 12.328 6.573 C 12.328 7.71 11.945 8.522 11.173 9.11 Z" fill="rgb(20, 20, 20)" height="21.335239490803623px" id="Qt9AxOqZR" transform="translate(156.099 5.338)" width="16.528666547835087px"/><path d="M 33.9 0.006 L 25.607 0.006 C 25.213 0.006 24.875 0.291 24.818 0.674 C 24.687 1.555 24.47 2.4 24.19 3.201 C 23.224 5.978 21.44 8.27 19.194 9.682 L 19.217 9.682 C 19.217 9.682 25.453 9.522 27.539 3.201 L 27.539 3.201 L 30.859 3.201 C 29.482 7.161 26.459 10.133 22.778 10.968 C 22.098 11.122 21.4 11.202 20.68 11.202 C 19.514 11.202 18.394 10.991 17.343 10.596 C 14.233 9.436 11.719 6.698 10.501 3.195 C 10.216 2.389 10.004 1.543 9.873 0.669 C 9.816 0.28 9.478 0 9.084 0 L 0.803 0 C 0.317 0 -0.061 0.434 0.008 0.914 C 0.117 1.697 0.277 2.458 0.488 3.201 C 2.3 9.687 7.672 14.397 14.005 14.403 C 10.924 13.357 6.106 10.436 3.837 3.201 L 3.837 3.201 L 3.837 3.201 L 7.158 3.201 C 8.027 6.298 9.707 9.002 11.919 10.968 C 13.496 12.374 15.342 13.408 17.354 13.957 C 18.423 14.248 19.543 14.403 20.692 14.403 C 27.03 14.403 32.408 9.687 34.22 3.201 C 34.426 2.463 34.586 1.697 34.7 0.914 C 34.769 0.434 34.391 0 33.906 0 Z" fill="rgb(20, 20, 20)" height="14.402572631835938px" id="yxyckXN6_" transform="translate(0 17.597)" width="34.708059114564385px"/><path d="M 0.803 14.403 L 9.095 14.403 C 9.49 14.403 9.827 14.117 9.884 13.734 C 10.016 12.854 10.233 12.008 10.513 11.208 C 11.479 8.43 13.256 6.138 15.497 4.727 L 15.479 4.727 C 15.479 4.727 9.244 4.887 7.158 11.208 L 7.158 11.208 L 3.837 11.208 L 3.837 11.208 C 5.209 7.247 8.238 4.269 11.913 3.435 C 12.593 3.281 13.29 3.201 14.011 3.201 C 15.176 3.201 16.297 3.412 17.348 3.806 C 20.457 4.967 22.972 7.704 24.19 11.208 L 24.19 11.208 L 24.19 11.208 C 24.475 12.014 24.687 12.859 24.818 13.734 C 24.875 14.123 25.213 14.403 25.607 14.403 L 33.9 14.403 C 34.386 14.403 34.763 13.968 34.694 13.488 C 34.586 12.711 34.426 11.945 34.214 11.202 C 32.408 4.721 27.024 0 20.686 0 C 23.767 1.046 28.59 3.961 30.865 11.208 L 30.865 11.208 L 27.544 11.208 L 27.544 11.208 L 27.544 11.208 C 26.681 8.104 24.995 5.407 22.784 3.435 C 21.206 2.029 19.36 1 17.354 0.446 C 16.28 0.154 15.165 0 14.016 0 C 7.672 0 2.294 4.721 0.488 11.208 L 0.488 11.208 L 0.488 11.208 C 0.282 11.951 0.122 12.711 0.008 13.494 C -0.061 13.974 0.317 14.408 0.803 14.408 Z" fill="rgb(20, 20, 20)" height="14.408287876490093px" id="fJajgayao" width="34.70234380798904px"/></g></svg>)