

Last updated: October 2026
For years, lenders could spot the warning signs of synthetic identity fraud and credit washing but struggled to act on them. A suspicious application might trigger an investigation, yet if that risk led to a credit denial, lenders often lacked a specific reason they could cite to the consumer.
Now, TransUnion is changing that. The credit reporting agency has launched the industry's first adverse-actionable Synthetic Fraud Score and Credit Washing Score, giving lenders reason codes they can use when these risks contribute to a credit decline. Oscilar's Agentic Risk Platform is the first platform to offer the new scores, bringing fraud intelligence directly into credit decisioning.
The launch addresses a longstanding disconnect in lending. Fraud teams could identify risks that traditional credit models missed, but the signals often lived in separate systems and lacked the explainability required for adverse action notices. Lenders were left relying on manual reviews, restrictive underwriting policies, or incomplete explanations for their decisions.
With TransUnion's new scores integrated into Oscilar, lenders can evaluate fraud and credit risk in the same workflow, act on suspicious applications, and carry the relevant reason codes into a single adverse action process. The result is more precise risk decisions, clearer explanations for consumers, and fewer operational hurdles between detecting fraud and acting on it.
TL;DR
Oscilar is first to offer TransUnion's industry-first fraud scores: The Synthetic Fraud Score and Credit Washing Score are the first adverse-actionable scores of their kind. Oscilar integrates both directly into credit decisioning workflows.
Lenders can now cite specific fraud risks in credit denials: Both scores include reason codes for adverse action notices. Lenders can decline suspected synthetic identities without first requiring failed manual identity verification and cite credit washing as a reason for denial for the first time.
Synthetic identity fraud creates $2.4 billion in lender exposure: TransUnion estimates that synthetic identities accounted for $2.4 billion in lender exposure as of June 2026, highlighting the risk of fabricated identities built from information that appears legitimate when checked individually.
Credit washing masks significantly higher charge-off risk: By suppressing negative credit history, credit washing makes risky applicants appear creditworthy. These consumers are 3.5 times more likely to charge off a new account within a year, with that risk rising to 10 times among super-prime consumers.
Targeted verification helps lenders distinguish fraud from legitimate applicants: Suspected synthetic identities can be routed to identity verification and potential credit washing to financial verification, giving lenders a way to investigate risk without automatically declining applicants with complex credit histories.
Oscilar connects fraud detection, verification, and credit decisions in one platform: Lenders can evaluate fraud and credit signals together, maintain a unified, auditable decision record, and carry relevant fraud reasons into adverse action notices. No-code workflows let risk teams refine policies across the customer lifecycle without engineering support.
Why this matters for lenders
Synthetic identity fraud and credit washing exploit different weaknesses in lending, but both can make a risky applicant appear creditworthy.
Synthetic identity fraud combines real and fabricated personal information into an identity that looks legitimate. Fraudsters build credit histories under these identities, season them for months or years before the bust-out, take out loans and disappear with the money.
Credit washing comes at it from the other side. The applicant suppresses accurate negative history, often through fraudulent disputes or false identity theft claims. The file that's left looks far more creditworthy than the repayment record behind it.
According to TransUnion, both risks carry substantive costs:
$2.4 billion in synthetic identity fraud exposure: Estimated total lender exposure as of June 2026.
3.5 times higher charge-off risk from credit washing: Consumers whose charge-offs were suppressed are 3.5 times more likely to charge off a new account within a year of opening it.
10 times higher risk among super prime consumers: The relative charge-off risk is sharpest among super prime consumers whose charge-offs were suppressed.
The trouble is that both kinds of fraud hide behind ordinary-looking credit profiles. A borrower can pass every standard check, because those checks were never built to see this.
"Synthetic identity fraud and credit washing present unique challenges because they can conceal risk behind seemingly legitimate consumer profiles," said James Garvert, Executive Vice President of Global Fraud and Communications Solutions at TransUnion. "By bringing advanced fraud intelligence into explainable, FCRA-governed decisioning, we're helping organizations uncover threats that might otherwise go undetected, make more confident decisions, and mitigate potential financial losses."
The missing link between fraud detection and credit decisions
Lenders have been able to flag these risks for years, but the harder problem was what to do when that information pointed toward a credit denial.
Fraud and credit teams typically worked in separate systems. A fraud model might identify a likely synthetic identity while the underwriting system evaluated the same application on conventional credit factors. Attackers exploit exactly those seams between siloed teams. And if the fraud finding did influence a denial, the lender still needed a specific, defensible reason to give the applicant.
Regulatory and contractual requirements made that hard. Many fraud scores from vendors outside the consumer reporting agency system weren't designed or authorized for credit eligibility decisions. They also lacked the specific reason codes Regulation B requires to explain an adverse action. An automated decline carries the same adverse action duties as one made by an underwriter, so a vague reason was never an option.
Earlier this year, a subprime lender's compliance counsel asked Oscilar how the institution could decline an applicant suspected of credit washing and cite that concern on the notice. The honest answer was that it couldn't. With the tools available at the time, there was no suitable reason code.
How lenders worked around the gap and what that cost borrowers
Without a straightforward way to bring these signals into credit decisions, lenders got conservative.
One large bank told Oscilar its first-party fraud losses looked low largely because it kept restrictive origination criteria. That kept losses down. It also meant turning away borrowers the bank would otherwise have wanted to serve.
Other institutions leaned on manual review. Analysts could investigate suspicious applications, request documentation or adjust terms. For a suspected synthetic identity, that review could end in a decline: if the applicant failed to verify their identity, the lender could decline for "unable to verify identity." But every one of those cases had to pass through the manual review queue first. Credit washing had no equivalent. Finding the concern didn't give the lender a usable reason code for a denial.
Legitimate applicants bore part of the cost. Borrowers with thin credit files or unusual financial histories got caught by stricter policies, and the same thin file that makes a synthetic identity hard to spot makes a genuine applicant easy to decline by mistake. Others waited through extra reviews. When an application was declined, the notice might explain the conventional credit factors without capturing the fraud concern behind the decision.
TransUnion's new scores give lenders a more precise option. The reason codes come from a consumer reporting agency, so lenders can bring these risks into credit decisions and explain them when they are principal reasons for a denial. Lenders can target suspicious applications directly. With the Synthetic Fraud Score, a lender can decline on synthetic identity risk outright, without routing every case through manual review. With the Credit Washing Score, the lender has a reason to cite that didn't exist before. Approval criteria no longer have to tighten for everyone.
What are TransUnion's new adverse-actionable fraud scores?
TransUnion's adverse-actionable synthetic identity and credit washing scores are two fraud scores a lender can use as a basis for declining credit and cite on the adverse action notice. TransUnion issues both as a consumer reporting agency with specific reason codes, which gives lenders the explainability a decline requires. Each score evaluates a different risk.
Synthetic Fraud Score: Catch fabricated identities before losses occur
TransUnion's Synthetic Fraud Score flags applications that may rely on identities built from real and fabricated information. Synthetic identities can build convincing credit histories. A standard credit check often misses them, because each piece of the identity verifies on its own.
The adverse-actionable version lets lenders bring synthetic identity risk into FCRA-governed credit decisions and cite the reason code when that risk supports a decline. In Oscilar, lenders can use the score to trigger additional identity verification, send the application to fraud analysts or feed the signal into credit policy.
Credit Washing Score: Find risk behind strong-looking credit files
TransUnion's Credit Washing Score flags elevated risk tied to suppressed negative credit history. An applicant whose past charge-offs have vanished from the report can look far less risky than their repayment record suggests.
The score supplies that missing context, with reason codes lenders can cite. In Oscilar's B2C credit underwriting workflows, lenders can use it to route applications to financial verification, inform underwriting policy and keep each credit decision explainable.
Different risks call for different responses
A synthetic can pass a credit review. A credit washer can pass an identity check. Each score answers a different question about the applicant and points to a different next step.
Risk type | What the score evaluates | Next step in Oscilar | Where the application goes |
|---|---|---|---|
Synthetic identity fraud | The score evaluates whether the applicant is a real person. | The lender asks for more identity proof, which makes this a KYC problem. | The application goes to the fraud queue. |
Credit washing | The score evaluates whether suppressed negative history is hiding credit risk. | The lender asks for more financial data to see the history the file no longer shows. | The application goes to the credit queue. |
Because the two risks differ, lenders can set a separate response for each. A general first-party fraud score can flag that something is wrong. It can't tell the lender what to do next, and it treats every flagged applicant the same way.
Oscilar is the first platform to offer TransUnion's new scores
The launch solves a real problem for lenders. Making the scores useful depends on what happens after the fraud signal arrives.
At many financial institutions, fraud detection, credit underwriting and compliance still run in separate systems. A new score may sharpen detection, but putting it into production can mean changes across several teams and workflows.
Oscilar's Agentic Risk Platform brings those functions together. As the first platform to offer TransUnion's new scores, Oscilar lets lenders evaluate synthetic identity and credit washing risk alongside their existing credit data, apply the right policies and connect the resulting decision to the adverse action process.
"A fraud score only pays off if the lender can act on it," said Neha Narkhede, co-founder and CEO of Oscilar, in the joint announcement. "TransUnion's adverse-actionable scores give lenders a reason they can cite, and Oscilar puts that reason on the same decision and notice as the credit reasons."
What this means in practice
Take an application that comes back with an elevated synthetic identity score. In Oscilar, that signal can trigger additional identity verification, route the case to a fraud analyst or, where the lender's policy calls for it, support a decline without a manual review. A high credit washing score might prompt financial verification or a closer underwriting review instead. Each application follows the path its particular risk calls for. Nobody gets the same blanket restriction.
When a score contributes to a credit denial, its reason can flow into the adverse action process alongside the traditional credit reasons. Oscilar's Decline Explanation agent helps teams build and validate the reason code mappings that turn those reasons into consumer-facing decline language. The signals evaluated, the policies applied and the final outcome land in a single decision record, so auditors get a clear account of how the decision was reached. That record is what lets a team replay a decision months later and explain every factor in it.
The intelligence stays useful after origination. A concern flagged during onboarding can inform later account reviews, and outcomes help fraud and credit teams refine their policies over time.
Fraud patterns change fast. Risk teams can adjust thresholds, add verification steps and modify decisioning logic in Oscilar's no-code workflows without waiting for an engineering release.
For Oscilar customers, the benefit goes beyond these two scores. New risk intelligence becomes part of the same decisioning process used across fraud, credit and the customer lifecycle. Teams can respond to the next threat without rebuilding the systems around each new signal.
Watch: TransUnion and Oscilar on what the new scores mean for lenders
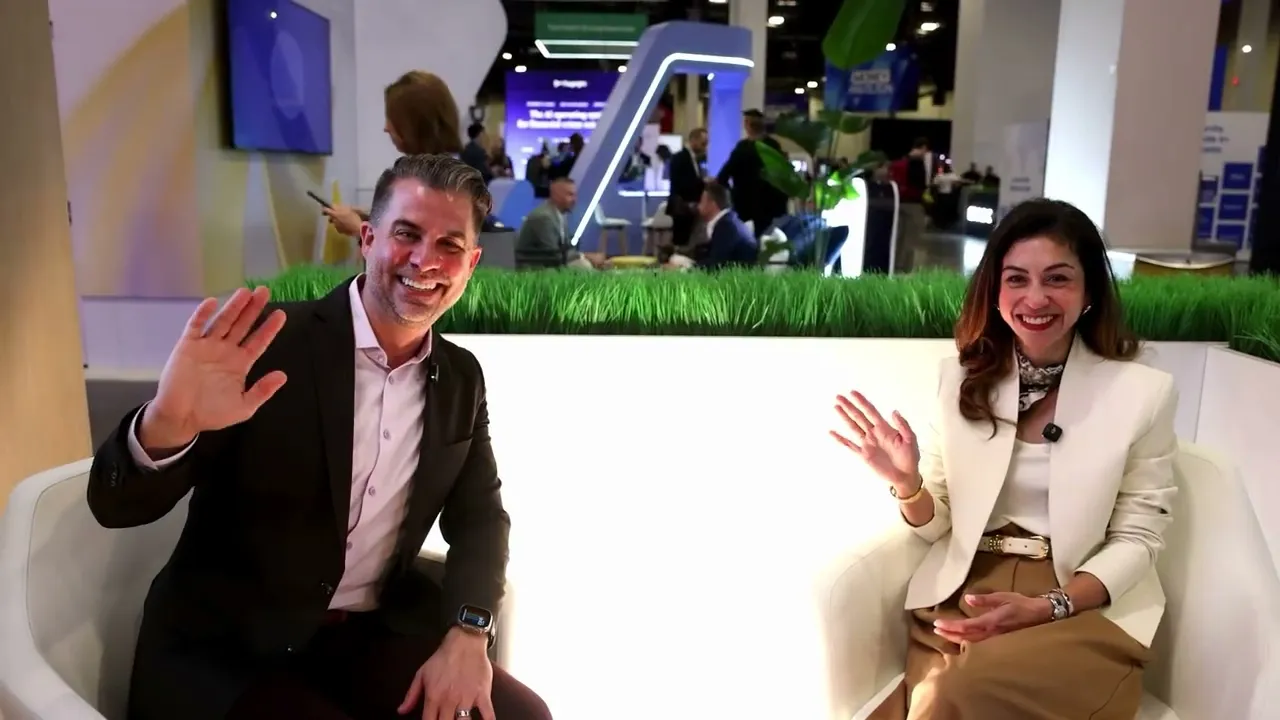
Jeffrey Johnston, Director of Global Fraud Strategy and Business Operations at TransUnion, sat down with Oscilar CEO Neha Narkhede at Money20/20 USA to discuss what the scores mean for lenders and the future of fraud and credit decisioning.
What TransUnion's scores mean for Oscilar customers
TransUnion's synthetic identity and credit washing scores turn two risks lenders could see into reasons lenders can cite. For Oscilar customers, the scores arrive in the same engine that runs credit decisioning, so each applicant goes down the right path and every decline carries a complete, auditable reason.
Already an Oscilar customer? Talk to your account team about adding the Synthetic Fraud Score and Credit Washing Score to your onboarding and credit workflows.
FAQs: Synthetic identity and credit washing scores
Can a lender decline an applicant for suspected synthetic identity fraud?
Yes. Declining on data from outside a consumer reporting agency is legal under FCRA section 615(b). A lender could always decline an applicant who failed identity verification, usually after a manual review, for a reason such as "unable to verify identity." What it couldn't do was decline on a fraud score itself, because most non-bureau fraud scores can't supply the specific reason Regulation B requires. TransUnion's Synthetic Fraud Score comes with specific reason codes, so a lender can decline on the score without sending the case through manual review first.
What is credit washing?
Credit washing is the removal of accurate negative information from a credit report, often through false claims of identity theft. The suppressed history makes an applicant look lower risk than they are. TransUnion analysis shows consumers whose charge-offs were suppressed through credit washing are 3.5 times more likely to charge off a new account within a year.
What has to appear on the adverse action notice when a fraud score contributes to a decline?
The fraud score's reason has to appear among the principal reasons on the notice, alongside the credit reasons. Because TransUnion issues the score as a consumer reporting agency, the notice also carries the FCRA section 615(a) disclosures.
Which risk platform offers TransUnion's adverse-actionable scores?
Oscilar's Agentic Risk Platform is the first platform to offer TransUnion's Credit Washing and Synthetic Fraud Scores with adverse action capability.
How do I use TransUnion's synthetic identity and credit washing scores in Oscilar?
Oscilar customers add the scores to the TransUnion call their onboarding or credit workflow already makes, then set routing rules for each risk type. A likely synthetic goes to identity verification and the fraud queue. Likely credit washing goes to financial verification and the credit queue. When a score contributes to a decline, its reason flows into the adverse action notice with the credit reasons.
How do the scores fit into an existing Oscilar credit workflow?
The TransUnion fraud reason code maps into an Oscilar workflow as another bureau-supplied reason, directly from the TransUnion API response. Risk teams then add routing rules for each risk type and send the fraud reason to the adverse action notice with the credit reasons.
Anurag Chowdhury
Director of Fraud and Risk
DISCLAIMER
The content on this website is provided for informational purposes only and does not constitute legal, tax, financial, investment, or other professional advice. Any views or opinions expressed by quoted individuals, contributors, or third parties are solely their own and do not necessarily reflect the views of our organization.
Nothing herein should be construed as an endorsement, recommendation, or approval of any particular strategy, product, service, or viewpoint. Readers should consult their own qualified advisors before making any financial or investment decisions.
Oscilar makes no representations or warranties as to the accuracy, completeness, or timeliness of the information provided and disclaims any liability for any loss or damage arising from reliance on this content. This website may contain links to third-party websites, which Oscilar does not control or endorse.


" height="48px" id="Qi9pnIQwR" width="48px"/></g></svg>)
" height="39.77194px" id="A8r2uGwai" transform="translate(2 3.808)" width="44px"/></svg>)


" height="22.301126233991734px" id="PeyDPUyWO" transform="translate(45.365 4.852)" width="20.043580159797898px"/><path d="M 13.46 11.116 C 12.368 10.493 10.888 9.973 9.024 9.556 C 7.664 9.236 6.613 8.927 5.887 8.624 C 5.155 8.321 4.647 7.979 4.355 7.59 C 4.064 7.201 3.921 6.704 3.921 6.104 C 3.921 5.184 4.269 4.447 4.972 3.898 C 5.675 3.349 6.624 3.069 7.83 3.069 C 8.79 3.069 9.607 3.241 10.282 3.578 C 10.951 3.921 11.482 4.401 11.876 5.018 C 12.265 5.641 12.511 6.361 12.614 7.184 L 16.1 6.973 C 15.94 5.63 15.523 4.435 14.854 3.383 C 14.185 2.332 13.265 1.503 12.105 0.903 C 10.945 0.303 9.539 0 7.899 0 C 6.355 0 5.024 0.263 3.904 0.783 C 2.783 1.303 1.92 2.035 1.32 2.978 C 0.72 3.921 0.417 5.001 0.417 6.224 C 0.417 7.344 0.646 8.281 1.109 9.036 C 1.572 9.785 2.315 10.419 3.349 10.928 C 4.384 11.436 5.755 11.905 7.481 12.328 C 9.024 12.688 10.19 13.059 10.985 13.442 C 11.774 13.825 12.311 14.237 12.591 14.688 C 12.871 15.14 13.014 15.666 13.014 16.266 C 13.014 16.906 12.848 17.455 12.517 17.906 C 12.185 18.358 11.705 18.695 11.076 18.912 C 10.448 19.135 9.676 19.243 8.779 19.243 C 7.739 19.243 6.847 19.072 6.104 18.735 C 5.361 18.392 4.778 17.883 4.344 17.203 C 3.915 16.523 3.629 15.689 3.486 14.711 L 0 14.923 C 0.103 16.403 0.514 17.7 1.246 18.798 C 1.977 19.901 2.972 20.764 4.235 21.381 C 5.498 22.004 6.99 22.313 8.71 22.313 C 10.27 22.313 11.636 22.061 12.797 21.564 C 13.957 21.061 14.871 20.341 15.528 19.398 C 16.191 18.455 16.523 17.346 16.523 16.06 C 16.523 15.02 16.289 14.094 15.814 13.282 C 15.346 12.471 14.563 11.756 13.471 11.133 Z" fill="rgb(20, 20, 20)" height="22.312556870217108px" id="ZaBOTiDLx" transform="translate(68.34 4.858)" width="16.522951309374434px"/><path d="M 13.682 17.877 C 12.751 18.792 11.442 19.243 9.762 19.243 C 8.522 19.243 7.43 18.923 6.504 18.283 C 5.572 17.643 4.847 16.723 4.326 15.517 C 3.806 14.317 3.543 12.871 3.543 11.191 C 3.543 9.51 3.801 8.093 4.309 6.876 C 4.818 5.664 5.544 4.727 6.487 4.064 C 7.43 3.401 8.533 3.069 9.79 3.069 C 11.373 3.069 12.619 3.486 13.534 4.315 C 14.443 5.149 15.031 6.281 15.294 7.727 L 18.901 7.544 C 18.438 5.178 17.472 3.332 16.003 2 C 14.528 0.669 12.459 0 9.796 0 C 7.83 0 6.115 0.457 4.641 1.366 C 3.166 2.28 2.029 3.572 1.217 5.241 C 0.406 6.916 0 8.893 0 11.179 C 0 13.465 0.412 15.494 1.235 17.146 C 2.058 18.798 3.201 20.072 4.675 20.964 C 6.15 21.855 7.847 22.301 9.767 22.301 C 11.528 22.301 13.054 21.975 14.334 21.324 C 15.614 20.672 16.654 19.752 17.443 18.558 C 18.232 17.363 18.758 15.957 19.021 14.334 L 15.443 14.151 C 15.203 15.711 14.614 16.952 13.682 17.86 Z" fill="rgb(20, 20, 20)" height="22.301126257066386px" id="dj2F9fN0f" transform="translate(87.772 4.841)" width="19.020540282808156px"/><path d="M 0 21.335 L 0 0 L 3.423 0 L 3.423 21.335 Z" fill="rgb(20, 20, 20)" height="21.335239445830055px" id="fvIs54YbW" transform="translate(110.485 5.332)" width="3.423468638642248px"/><path d="M 3.429 0 L 0 0 L 0 21.341 L 13.762 21.341 L 13.762 18.272 L 3.429 18.272 Z" fill="rgb(20, 20, 20)" height="21.340954752405395px" id="KykvynROU" transform="translate(118.389 5.332)" width="13.762458233473922px"/><path d="M 9.859 3.303 L 16.077 21.335 L 19.684 21.335 L 11.991 0 L 7.693 0 L 0 21.335 L 3.635 21.335 L 9.853 3.303 Z" fill="rgb(20, 20, 20)" height="21.33523944583004px" id="Ln_a1JZTX" transform="translate(133.986 5.338)" width="19.683515845550573px"/><path d="M 11.545 12.499 C 12.968 12.059 14.043 11.322 14.774 10.293 C 15.506 9.259 15.871 8.024 15.871 6.584 C 15.871 4.521 15.191 2.909 13.825 1.743 C 12.465 0.583 10.539 0 8.053 0 L 0 0 L 0 21.335 L 3.423 21.335 L 3.423 13.071 L 8.201 13.071 L 12.802 21.335 L 16.529 21.335 L 11.539 12.499 Z M 11.173 9.116 C 10.402 9.705 9.327 10.002 7.944 10.002 L 3.435 10.002 L 3.435 3.058 L 7.944 3.058 C 9.327 3.058 10.402 3.361 11.173 3.961 C 11.945 4.561 12.328 5.435 12.328 6.573 C 12.328 7.71 11.945 8.522 11.173 9.11 Z" fill="rgb(20, 20, 20)" height="21.335239490803623px" id="Qt9AxOqZR" transform="translate(156.099 5.338)" width="16.528666547835087px"/><path d="M 33.9 0.006 L 25.607 0.006 C 25.213 0.006 24.875 0.291 24.818 0.674 C 24.687 1.555 24.47 2.4 24.19 3.201 C 23.224 5.978 21.44 8.27 19.194 9.682 L 19.217 9.682 C 19.217 9.682 25.453 9.522 27.539 3.201 L 27.539 3.201 L 30.859 3.201 C 29.482 7.161 26.459 10.133 22.778 10.968 C 22.098 11.122 21.4 11.202 20.68 11.202 C 19.514 11.202 18.394 10.991 17.343 10.596 C 14.233 9.436 11.719 6.698 10.501 3.195 C 10.216 2.389 10.004 1.543 9.873 0.669 C 9.816 0.28 9.478 0 9.084 0 L 0.803 0 C 0.317 0 -0.061 0.434 0.008 0.914 C 0.117 1.697 0.277 2.458 0.488 3.201 C 2.3 9.687 7.672 14.397 14.005 14.403 C 10.924 13.357 6.106 10.436 3.837 3.201 L 3.837 3.201 L 3.837 3.201 L 7.158 3.201 C 8.027 6.298 9.707 9.002 11.919 10.968 C 13.496 12.374 15.342 13.408 17.354 13.957 C 18.423 14.248 19.543 14.403 20.692 14.403 C 27.03 14.403 32.408 9.687 34.22 3.201 C 34.426 2.463 34.586 1.697 34.7 0.914 C 34.769 0.434 34.391 0 33.906 0 Z" fill="rgb(20, 20, 20)" height="14.402572631835938px" id="yxyckXN6_" transform="translate(0 17.597)" width="34.708059114564385px"/><path d="M 0.803 14.403 L 9.095 14.403 C 9.49 14.403 9.827 14.117 9.884 13.734 C 10.016 12.854 10.233 12.008 10.513 11.208 C 11.479 8.43 13.256 6.138 15.497 4.727 L 15.479 4.727 C 15.479 4.727 9.244 4.887 7.158 11.208 L 7.158 11.208 L 3.837 11.208 L 3.837 11.208 C 5.209 7.247 8.238 4.269 11.913 3.435 C 12.593 3.281 13.29 3.201 14.011 3.201 C 15.176 3.201 16.297 3.412 17.348 3.806 C 20.457 4.967 22.972 7.704 24.19 11.208 L 24.19 11.208 L 24.19 11.208 C 24.475 12.014 24.687 12.859 24.818 13.734 C 24.875 14.123 25.213 14.403 25.607 14.403 L 33.9 14.403 C 34.386 14.403 34.763 13.968 34.694 13.488 C 34.586 12.711 34.426 11.945 34.214 11.202 C 32.408 4.721 27.024 0 20.686 0 C 23.767 1.046 28.59 3.961 30.865 11.208 L 30.865 11.208 L 27.544 11.208 L 27.544 11.208 L 27.544 11.208 C 26.681 8.104 24.995 5.407 22.784 3.435 C 21.206 2.029 19.36 1 17.354 0.446 C 16.28 0.154 15.165 0 14.016 0 C 7.672 0 2.294 4.721 0.488 11.208 L 0.488 11.208 L 0.488 11.208 C 0.282 11.951 0.122 12.711 0.008 13.494 C -0.061 13.974 0.317 14.408 0.803 14.408 Z" fill="rgb(20, 20, 20)" height="14.408287876490093px" id="fJajgayao" width="34.70234380798904px"/></g></svg>)