Trusted by institutions building next-gen finance


detection
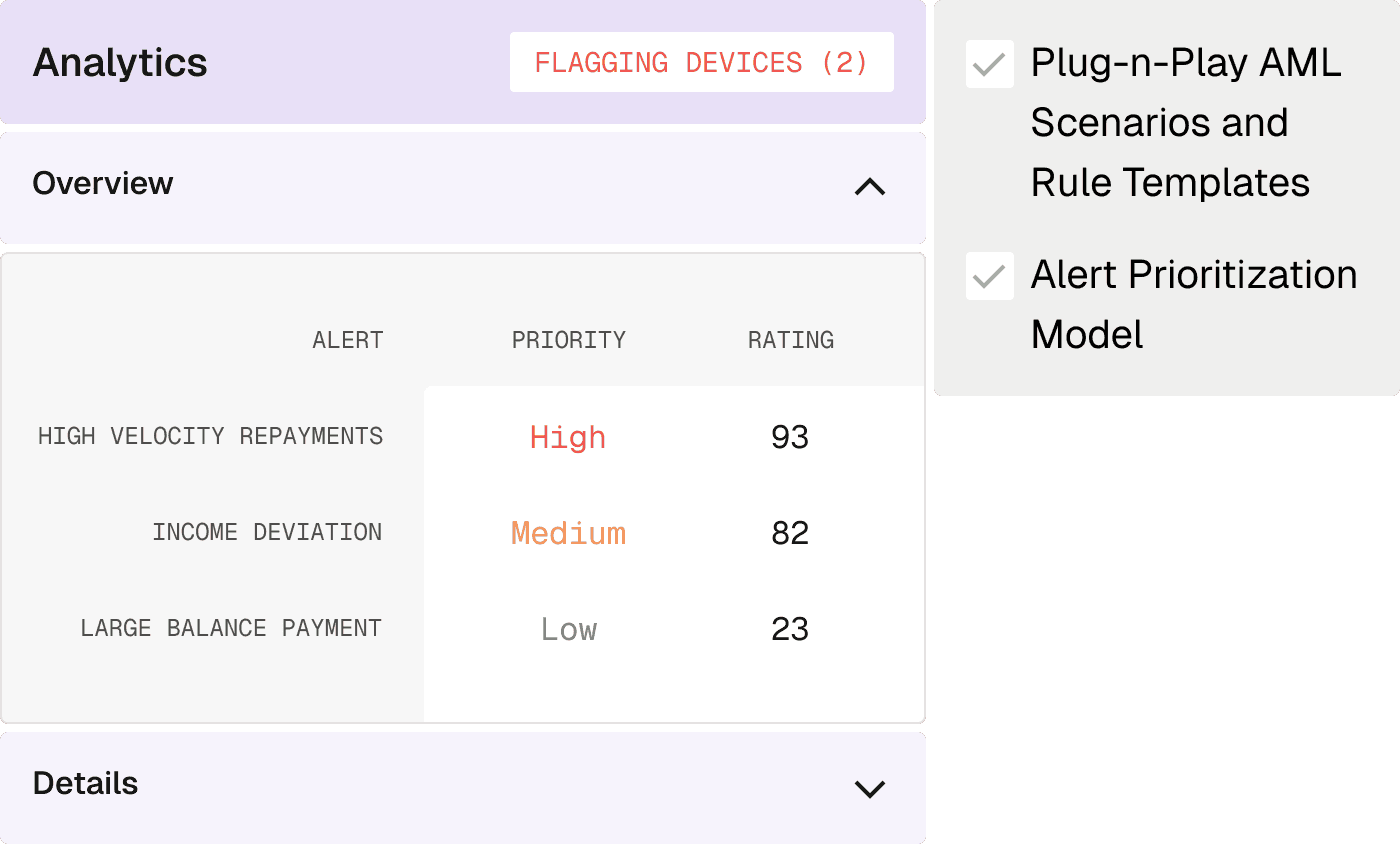
Score every payment in real time, across every rail.
Batch monitoring tells you about last night. Real-time scoring lets you hold a payment before it settles, on the same models and the same rules.
Real-time scoring across ACH, wire, card, wallet and SWIFT payments
Pre-built typology rulesets you can edit without a release
Behavioral models with 95% detection accuracy that score the customer, not only the payment
Continuous learning as new typologies appear
false positives
Tune thresholds against your own alert history, not a vendor default.
Every threshold change can be back-tested against your own data first, so you see what it would have caught and what it would have missed before it goes live.
Back-test any rule change against historical alerts
Segment thresholds by product, channel and customer risk
Backtest a threshold change in one click and see the alert volume it produces before you ship it
Keep a versioned record of every threshold change
investigation and SAR filing
Investigate and e-file without leaving the alert.
The case, the customer history, the related alerts and the filing all sit in one place, so an investigation does not open with fifteen minutes of gathering.
One queue for every alert, with context attached
Related-party and network view on the customer
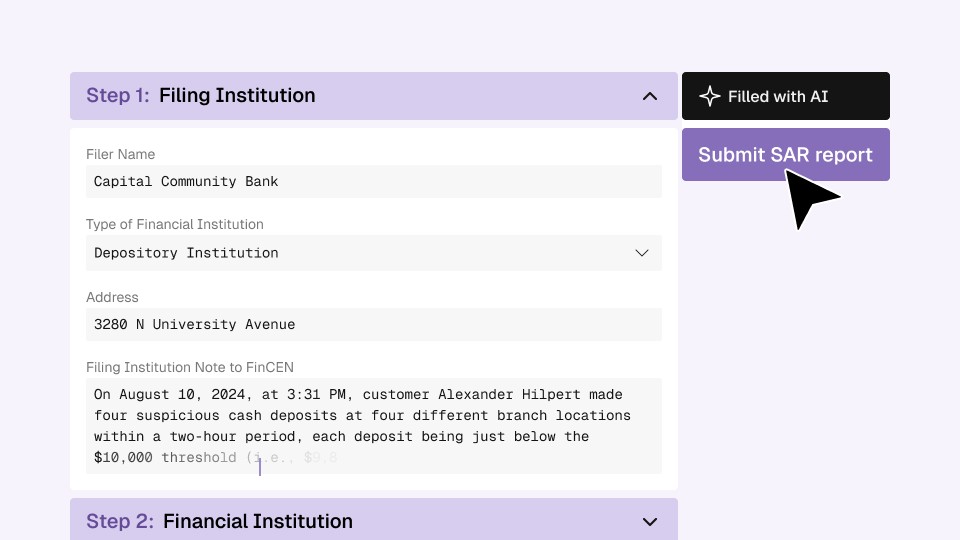
Pre-populated SAR templates and direct FinCEN e-filing
An audit trail from alert through investigation to filing


Explainable scores
Each alert names the features that drove it, in language an investigator and an examiner can both read.

Validation and tuning records
Every model version, every threshold change, who approved it and what the back-test showed, kept together so an examiner review is a lookup rather than a reconstruction.
Audit trail
An unbroken record from the transaction through the alert and the investigation to the filing.

Fewer false positives
Analysts clear alerts 3x faster and spend their time on the ones that turn into something.

Changes ship the same day
Update a rule or a threshold without a vendor ticket and without waiting for a release cycle.

One platform for fraud and AML
The same engine scores fraud and money laundering, so the two teams see one customer rather than two.
Customers see results with Oscilar.


FAQ
Glad you asked.
What is AML transaction monitoring software?
AML transaction monitoring software reviews customer and account activity to find patterns that may indicate money laundering, then routes what it finds to an investigator. It covers the whole path: ingesting payments and the customer data around them, scoring activity against rules and models, raising an alert with enough context to work, and producing the suspicious activity report if the investigation supports one. Banks and fintechs run it because the Bank Secrecy Act requires a risk-based program, and examiners expect to see that the rules and models behind it are owned, documented and tested.
How is real-time monitoring different from batch monitoring?
Batch monitoring scores activity after the fact, usually overnight, so the first chance to act is the next morning. Real-time monitoring scores a payment as it moves, which means a transaction can be held, stepped up or released before it settles. For AML reporting the difference is smaller than it sounds, because a SAR is filed on a deadline rather than in the moment. Where it matters is the overlap with fraud: on instant rails there is no post-settlement recovery, so a decision made after the batch runs is a decision made too late.
How does AI reduce false positives without missing suspicious activity?
A fixed threshold treats every customer the same, so ordinary behavior for one account looks anomalous on another and the alert queue fills with activity nobody needed to see. Models score activity against what is normal for that customer and that segment, which narrows the queue without lowering the bar. The safeguard is testing rather than trust: a threshold change should be back-tested against historical alerts so you can see what it would have suppressed before it ships. Reducing false positives should come from better context, never from quietly suppressing alerts.
What is involved in replacing a legacy transaction monitoring system?
It does not have to be a replacement on day one. A bank can keep its upstream data sources and its incumbent system while running a new platform alongside it, comparing the two on the same activity until the coverage is proven. That parallel run is what gives model risk management something to review and what makes the eventual cutover defensible to an examiner. It also moves faster than most teams expect: Oscilar's AML Alert Triage agent typically deploys within 2 to 4 weeks, and Balance went from contract to full production in 32 days when it replaced a sunsetting platform.
How do you evidence a model decision to an examiner?
You need to be able to say who owns each rule and model, what version was running on a given date, what changed, who approved it, and how it was tested before it shipped. On an individual alert you need the reasons the score was what it was, in language a person can read. Keep the version history, the approval record, the back-test results and the ongoing performance monitoring together, and an examiner review becomes a matter of retrieving records rather than reconstructing them.
Does transaction monitoring cover fraud as well as money laundering?
They are usually separate systems and separate teams, which is why the same customer can be a fraud case in one queue and an AML case in another with neither team seeing both. Running them on one engine, sometimes called FRAML, gives you one view of the customer and one case standard, and the signals genuinely overlap: mule activity, account takeover and first-party fraud all leave patterns that matter to both. Oscilar scores fraud and AML on the same platform, so the two queues are views of one customer rather than two.
" height="48px" id="Qi9pnIQwR" width="48px"/></g></svg>)
" height="39.77194px" id="A8r2uGwai" transform="translate(2 3.808)" width="44px"/></svg>)


" height="22.301126233991734px" id="PeyDPUyWO" transform="translate(45.365 4.852)" width="20.043580159797898px"/><path d="M 13.46 11.116 C 12.368 10.493 10.888 9.973 9.024 9.556 C 7.664 9.236 6.613 8.927 5.887 8.624 C 5.155 8.321 4.647 7.979 4.355 7.59 C 4.064 7.201 3.921 6.704 3.921 6.104 C 3.921 5.184 4.269 4.447 4.972 3.898 C 5.675 3.349 6.624 3.069 7.83 3.069 C 8.79 3.069 9.607 3.241 10.282 3.578 C 10.951 3.921 11.482 4.401 11.876 5.018 C 12.265 5.641 12.511 6.361 12.614 7.184 L 16.1 6.973 C 15.94 5.63 15.523 4.435 14.854 3.383 C 14.185 2.332 13.265 1.503 12.105 0.903 C 10.945 0.303 9.539 0 7.899 0 C 6.355 0 5.024 0.263 3.904 0.783 C 2.783 1.303 1.92 2.035 1.32 2.978 C 0.72 3.921 0.417 5.001 0.417 6.224 C 0.417 7.344 0.646 8.281 1.109 9.036 C 1.572 9.785 2.315 10.419 3.349 10.928 C 4.384 11.436 5.755 11.905 7.481 12.328 C 9.024 12.688 10.19 13.059 10.985 13.442 C 11.774 13.825 12.311 14.237 12.591 14.688 C 12.871 15.14 13.014 15.666 13.014 16.266 C 13.014 16.906 12.848 17.455 12.517 17.906 C 12.185 18.358 11.705 18.695 11.076 18.912 C 10.448 19.135 9.676 19.243 8.779 19.243 C 7.739 19.243 6.847 19.072 6.104 18.735 C 5.361 18.392 4.778 17.883 4.344 17.203 C 3.915 16.523 3.629 15.689 3.486 14.711 L 0 14.923 C 0.103 16.403 0.514 17.7 1.246 18.798 C 1.977 19.901 2.972 20.764 4.235 21.381 C 5.498 22.004 6.99 22.313 8.71 22.313 C 10.27 22.313 11.636 22.061 12.797 21.564 C 13.957 21.061 14.871 20.341 15.528 19.398 C 16.191 18.455 16.523 17.346 16.523 16.06 C 16.523 15.02 16.289 14.094 15.814 13.282 C 15.346 12.471 14.563 11.756 13.471 11.133 Z" fill="rgb(20, 20, 20)" height="22.312556870217108px" id="ZaBOTiDLx" transform="translate(68.34 4.858)" width="16.522951309374434px"/><path d="M 13.682 17.877 C 12.751 18.792 11.442 19.243 9.762 19.243 C 8.522 19.243 7.43 18.923 6.504 18.283 C 5.572 17.643 4.847 16.723 4.326 15.517 C 3.806 14.317 3.543 12.871 3.543 11.191 C 3.543 9.51 3.801 8.093 4.309 6.876 C 4.818 5.664 5.544 4.727 6.487 4.064 C 7.43 3.401 8.533 3.069 9.79 3.069 C 11.373 3.069 12.619 3.486 13.534 4.315 C 14.443 5.149 15.031 6.281 15.294 7.727 L 18.901 7.544 C 18.438 5.178 17.472 3.332 16.003 2 C 14.528 0.669 12.459 0 9.796 0 C 7.83 0 6.115 0.457 4.641 1.366 C 3.166 2.28 2.029 3.572 1.217 5.241 C 0.406 6.916 0 8.893 0 11.179 C 0 13.465 0.412 15.494 1.235 17.146 C 2.058 18.798 3.201 20.072 4.675 20.964 C 6.15 21.855 7.847 22.301 9.767 22.301 C 11.528 22.301 13.054 21.975 14.334 21.324 C 15.614 20.672 16.654 19.752 17.443 18.558 C 18.232 17.363 18.758 15.957 19.021 14.334 L 15.443 14.151 C 15.203 15.711 14.614 16.952 13.682 17.86 Z" fill="rgb(20, 20, 20)" height="22.301126257066386px" id="dj2F9fN0f" transform="translate(87.772 4.841)" width="19.020540282808156px"/><path d="M 0 21.335 L 0 0 L 3.423 0 L 3.423 21.335 Z" fill="rgb(20, 20, 20)" height="21.335239445830055px" id="fvIs54YbW" transform="translate(110.485 5.332)" width="3.423468638642248px"/><path d="M 3.429 0 L 0 0 L 0 21.341 L 13.762 21.341 L 13.762 18.272 L 3.429 18.272 Z" fill="rgb(20, 20, 20)" height="21.340954752405395px" id="KykvynROU" transform="translate(118.389 5.332)" width="13.762458233473922px"/><path d="M 9.859 3.303 L 16.077 21.335 L 19.684 21.335 L 11.991 0 L 7.693 0 L 0 21.335 L 3.635 21.335 L 9.853 3.303 Z" fill="rgb(20, 20, 20)" height="21.33523944583004px" id="Ln_a1JZTX" transform="translate(133.986 5.338)" width="19.683515845550573px"/><path d="M 11.545 12.499 C 12.968 12.059 14.043 11.322 14.774 10.293 C 15.506 9.259 15.871 8.024 15.871 6.584 C 15.871 4.521 15.191 2.909 13.825 1.743 C 12.465 0.583 10.539 0 8.053 0 L 0 0 L 0 21.335 L 3.423 21.335 L 3.423 13.071 L 8.201 13.071 L 12.802 21.335 L 16.529 21.335 L 11.539 12.499 Z M 11.173 9.116 C 10.402 9.705 9.327 10.002 7.944 10.002 L 3.435 10.002 L 3.435 3.058 L 7.944 3.058 C 9.327 3.058 10.402 3.361 11.173 3.961 C 11.945 4.561 12.328 5.435 12.328 6.573 C 12.328 7.71 11.945 8.522 11.173 9.11 Z" fill="rgb(20, 20, 20)" height="21.335239490803623px" id="Qt9AxOqZR" transform="translate(156.099 5.338)" width="16.528666547835087px"/><path d="M 33.9 0.006 L 25.607 0.006 C 25.213 0.006 24.875 0.291 24.818 0.674 C 24.687 1.555 24.47 2.4 24.19 3.201 C 23.224 5.978 21.44 8.27 19.194 9.682 L 19.217 9.682 C 19.217 9.682 25.453 9.522 27.539 3.201 L 27.539 3.201 L 30.859 3.201 C 29.482 7.161 26.459 10.133 22.778 10.968 C 22.098 11.122 21.4 11.202 20.68 11.202 C 19.514 11.202 18.394 10.991 17.343 10.596 C 14.233 9.436 11.719 6.698 10.501 3.195 C 10.216 2.389 10.004 1.543 9.873 0.669 C 9.816 0.28 9.478 0 9.084 0 L 0.803 0 C 0.317 0 -0.061 0.434 0.008 0.914 C 0.117 1.697 0.277 2.458 0.488 3.201 C 2.3 9.687 7.672 14.397 14.005 14.403 C 10.924 13.357 6.106 10.436 3.837 3.201 L 3.837 3.201 L 3.837 3.201 L 7.158 3.201 C 8.027 6.298 9.707 9.002 11.919 10.968 C 13.496 12.374 15.342 13.408 17.354 13.957 C 18.423 14.248 19.543 14.403 20.692 14.403 C 27.03 14.403 32.408 9.687 34.22 3.201 C 34.426 2.463 34.586 1.697 34.7 0.914 C 34.769 0.434 34.391 0 33.906 0 Z" fill="rgb(20, 20, 20)" height="14.402572631835938px" id="yxyckXN6_" transform="translate(0 17.597)" width="34.708059114564385px"/><path d="M 0.803 14.403 L 9.095 14.403 C 9.49 14.403 9.827 14.117 9.884 13.734 C 10.016 12.854 10.233 12.008 10.513 11.208 C 11.479 8.43 13.256 6.138 15.497 4.727 L 15.479 4.727 C 15.479 4.727 9.244 4.887 7.158 11.208 L 7.158 11.208 L 3.837 11.208 L 3.837 11.208 C 5.209 7.247 8.238 4.269 11.913 3.435 C 12.593 3.281 13.29 3.201 14.011 3.201 C 15.176 3.201 16.297 3.412 17.348 3.806 C 20.457 4.967 22.972 7.704 24.19 11.208 L 24.19 11.208 L 24.19 11.208 C 24.475 12.014 24.687 12.859 24.818 13.734 C 24.875 14.123 25.213 14.403 25.607 14.403 L 33.9 14.403 C 34.386 14.403 34.763 13.968 34.694 13.488 C 34.586 12.711 34.426 11.945 34.214 11.202 C 32.408 4.721 27.024 0 20.686 0 C 23.767 1.046 28.59 3.961 30.865 11.208 L 30.865 11.208 L 27.544 11.208 L 27.544 11.208 L 27.544 11.208 C 26.681 8.104 24.995 5.407 22.784 3.435 C 21.206 2.029 19.36 1 17.354 0.446 C 16.28 0.154 15.165 0 14.016 0 C 7.672 0 2.294 4.721 0.488 11.208 L 0.488 11.208 L 0.488 11.208 C 0.282 11.951 0.122 12.711 0.008 13.494 C -0.061 13.974 0.317 14.408 0.803 14.408 Z" fill="rgb(20, 20, 20)" height="14.408287876490093px" id="fJajgayao" width="34.70234380798904px"/></g></svg>)